$4.8bn financing gap threatens SME growth – BoG
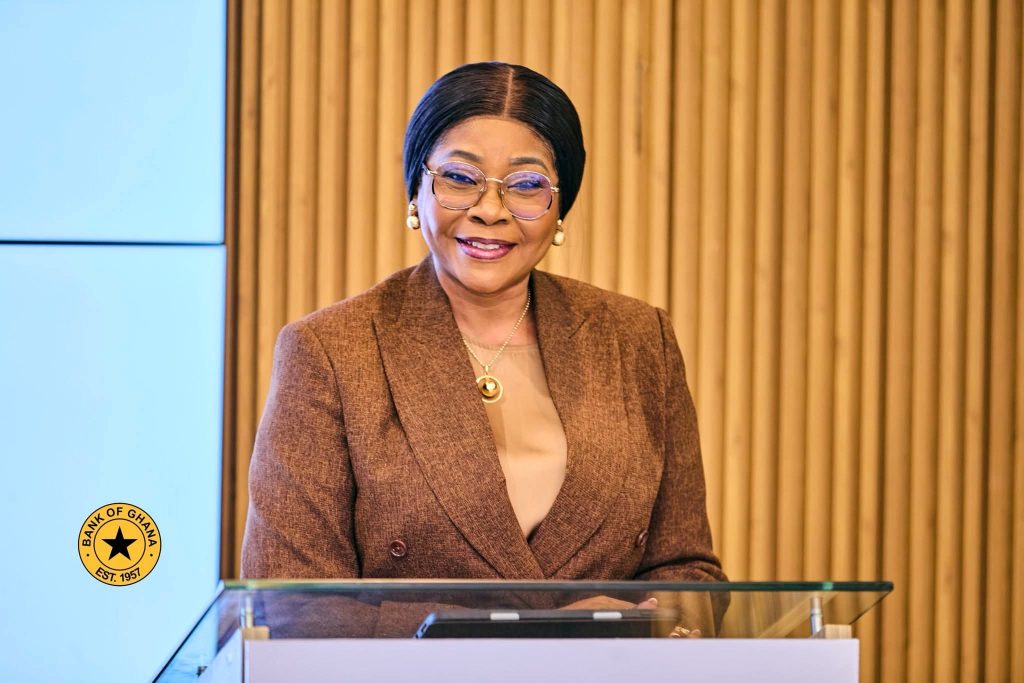
Second Deputy Governor of the Bank of Ghana, Matilda Asante-Asiedu
Ghana’s small and medium-sized enterprises (SMEs) are facing an estimated US$4.8 billion annual financing gap, despite the rapid expansion of digital payments across the country, the Bank of Ghana (BoG) has disclosed.
The situation, according to the central bank, highlights a major weakness in Ghana’s financial system: businesses can increasingly receive and make digital payments within seconds, but many still struggle to obtain the working capital needed to operate, expand and create jobs.
Second Deputy Governor of the Bank of Ghana, Matilda Asante-Asiedu, said the country had developed a sophisticated digital payments infrastructure but had yet to build an equally effective system for translating digital transaction records into credit.
“We have built extraordinary payment rails, but we have not yet built equally extraordinary credit rails,” she said.
She made the remarks at the University of Ghana during the National ICT Week celebration, where she delivered the third Distinguished Digital Finance Lecture.
The financing gap has potentially serious consequences for Ghana’s economic development because SMEs constitute a major part of business activity and employment.
Without adequate access to affordable financing, otherwise viable businesses may be unable to purchase inventory, pay workers, invest in equipment, take advantage of new contracts or expand into new markets.
Digital payments, limited credit
Ms Asante-Asiedu said the disconnect between digital payments and access to credit was particularly troubling because Ghana already had significant financial resources within its banking, pension and investment sectors.
She described the inability to connect those resources with the financial needs of businesses as a major missed opportunity.
“The disconnect between transaction data and credit access, in my view, is the single largest unrealized opportunity in this room,” she said.
An SME operator, for instance, could receive payments from customers through an instant digital
payment platform almost immediately, yet face months of delays when applying for working capital.
The consequences can be severe. Businesses that cannot secure financing when needed may lose contracts, reduce production, delay salary payments, scale down operations or abandon expansion plans.
For smaller businesses with limited cash reserves, prolonged difficulty in accessing credit can also increase the risk of closure.
Transaction data as new collateral
The Second Deputy Governor argued that digital transaction histories should increasingly become part of how financial institutions assess creditworthiness.
She said mobile money and other digital payment records could provide lenders with detailed information about a business, including transaction volumes, frequency of payments, merchant activity, income patterns and changes in business performance.
“This is not just background information. It is a credit record. We have simply not built the habit of reading it as such,” she said.
Such information could be particularly valuable for SMEs that lack conventional collateral.
Ms Asante-Asiedu challenged the traditional dependence on land and buildings as the primary security for loans, pointing out that much of the value generated by modern businesses exists in contracts, receivables, purchase orders and transaction histories.
Confirmed purchase orders, export contracts and long-term service agreements, she said, could provide verifiable evidence of future income and support lending decisions if the appropriate legal and regulatory framework were established.
SMEs paying the price
The current financing constraints could have wider economic implications beyond individual businesses.
When SMEs struggle to obtain affordable working capital, their ability to hire additional workers, increase production and invest in technology is weakened.
This can limit job creation and reduce the contribution of smaller enterprises to economic growth.
Businesses may also be forced to rely on expensive informal sources of finance, which can increase operating costs and undermine profitability.
For businesses with seasonal or irregular cash flows, the absence of timely credit can be especially damaging because opportunities may disappear before financing is secured.
The situation also risks widening the gap between established companies with assets and financial records and smaller businesses that have strong cash flows but lack conventional collateral.
Ghana has the digital foundation
Ms Asante-Asiedu pointed to the extraordinary growth of Ghana’s digital payments ecosystem as evidence that the country already possesses much of the infrastructure required to transform digital finance.
Mobile money platforms processed 954 million transactions valued at approximately GH¢493 billion in June 2026 alone, she said.
Ghana also had about 84.6 million registered mobile money accounts, although only 26.4 million were active, supported by more than one million registered agents.
The challenge, she said, was now to move beyond using digital platforms primarily for payments and leverage the data generated through those transactions to expand access to productive credit.
BoG pushes open banking
The Bank of Ghana is consequently advancing open banking and open finance frameworks to help unlock financing for SMEs.
Ms Asante-Asiedu said the success of open banking should not be measured simply by the number of application programming interfaces (APIs) developed or systems connected.
Instead, the key test should be whether the systems result in more affordable and accessible credit reaching small businesses.
“The measure of success…should be how much credit” reaches businesses through the use of transaction data, she said.
She acknowledged, however, that several obstacles must be addressed, including regulatory fragmentation, cybersecurity risks, data governance and inadequate digital infrastructure.
READ ALSO:COCOBOD sets Aug. 27 light crop deadline
The central bank is therefore expected to continue working with other financial regulators and stakeholders to strengthen coordination and create safeguards that allow digital finance to expand without exposing consumers and businesses to unnecessary risks.
For Ghana’s SMEs, the urgency is clear. The country has built a digital payment system capable of moving hundreds of billions of cedis, but unless that digital activity can be converted into affordable working capital, thousands of businesses will continue to face a debilitating financing constraint.
The US$4.8 billion gap therefore represents more than a financial statistic. It is a warning that Ghana’s digital transformation risks remaining incomplete unless the ability to move money is matched by the ability to access the credit needed to invest, grow and create jobs.
About The Author